Credit life insurance is one of the best ways to protect a farmer’s assets in the event of death, disability, or terminal illness. This type of insurance plan repays the borrower’s outstanding agricultural credit loan.
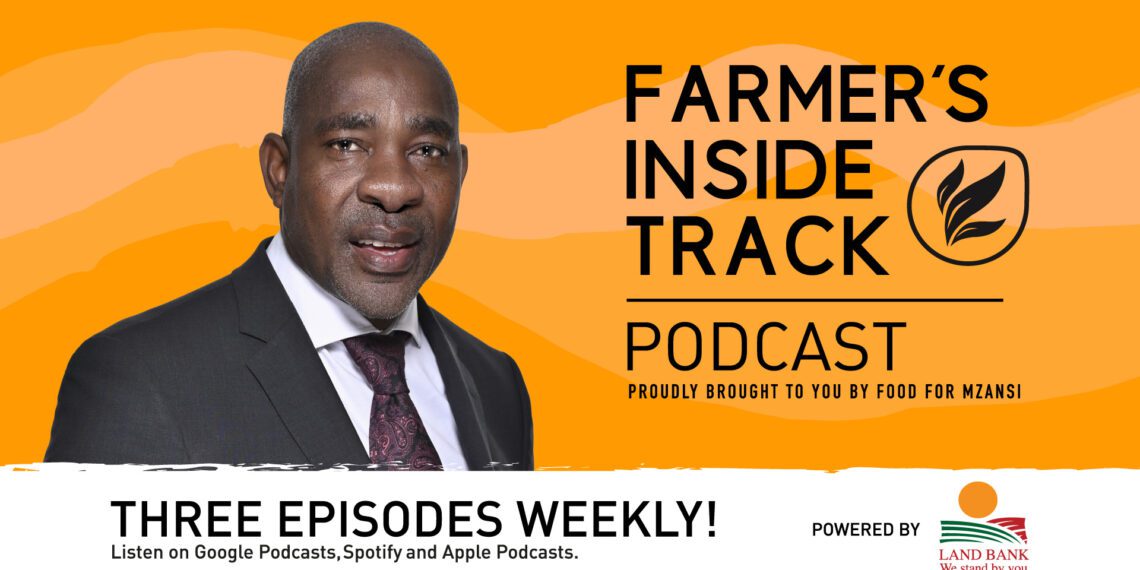
Pascal Siphugu, general director of Land Bank Insurance Company (LBIC), shares how credit life insurance works and how it can provide financial peace of mind when farmers borrow large sums of money to fund agricultural activities.
“Credit [life] insurance policies are typically a requirement for funders when they grant loans but also very important for the farmer to mitigate against health risks and the dire consequences of leaving the family with a burden of debt from funders,” he says.
Terms and conditions
LBLIC can provide farmers with a credit life insurance policy with a flat or a declining term, which means that LBLIC offers flexibility to farmers.
Siphugu also cautions farmers against skipping payments as non-payment holds dire consequences for the farmer. “The policy lapses after the non-payment of two consecutive premium payments. Policies reinstated within two months will have no conditions applicable.”
In this episode, Siphugu also discusses:
- Credit life insurance requirements;
- Why this is a highly recommended cover; and
- What happens when no payment is made?
Want to know more? Listen to the full episode of Farmer’s Inside Track.
Option 1: Click here to listen on Spotify (all mobile and other devices).
Option 2: Click here to listen on any Apple device.
Option 3: Click here to listen on Google Podcast.
READ NEXT: Safeguard your harvest with Land Bank’s credit life insurance
Sign up for Farmer’s Inside Track: Join our exclusive platform for new entrants into farming and agri-business, with newsletters and podcasts.